The second counterargument is that the future may be different from the past, and that, despite the long historical record, the safe interest rate may become consistently higher than the growth rate. History may indeed not be a reliable guide to the future. As the debate on secular stagnation and the level of the long run Wicksellian rate (the safe rate consistent with unemployment remaining at the natural rate) indicate, the future is indeed uncertain. It may be that some of the 40This trade-off is also present in Angeletos et al (2016).
第二の反論は、未来は過去とは異なり、長い歴史的記録にもかかわらず、安全金利は成長率より一貫して高くなる可能性があるというものである。歴史は確かに未来への信頼できるガイドではないかもしれない。世俗的停滞や長期金利(失業率が自然率で推移する場合の安全金利)水準に関する議論が示すように、将来は実に不確かである。Angeletos et al (2016)にも、40This trade-off の一部が存在するのかもしれない。
p.36
VII. Conclusions
In this lecture, I have looked at the fiscal and welfare costs of higher debt in an economy where the safe interest rate is less than the growth rate. I have argued that this is a relevant empirical configuration, and indeed has been the norm rather than the exception in the United States in the past. I have argued that both the fiscal and welfare costs of debt may then be small, smaller than is generally taken as given in current policy discussions. I have considered a number of counterarguments, which are indeed valid, and may imply larger fiscal and welfare costs. The purpose of this lecture is most definitely not to argue for higher debt per se, but to allow for a richer discussion of debt policy and appropriate debt rules than is currently the case.
The sustainability of fiscal policy as determined via the orthodox IGBC framework is irrelevant for understanding the workings of a modern money economy. The orthodox framework’s assumption that interest rates are determined in a loanable funds market for interest rate determination and the related assumption of differing inflationary impacts of “monetization” versus the “financing” of deficits are both fundamentally flawed. Instead, the orthodox view that fiscal deficits or international forces might have large effects on interest rates could be appropriate only for a non-sovereign-currency-issuing government operating under fixed exchange rates, not for a modern money regime with flexible exchange rates (Wray, 2006a). Consistent with the monetary nature of interest rates in a modern money regime, rates on Treasuries have followed the stance of monetary policy, not fiscal policy, and have only risen above the rate of GDP growth during times when high interest rate policies were set in place by monetary policy makers. And because interest rates on the national debt in a modern money regime are a matter of monetary policy, it follows that the stance of monetary policy has much to do with whether a given fiscal path is “sustainable” or not. The “sound finance” view of fiscal policy is obviously central to the orthodox view of fiscal sustainability. As Blanchard et al. (1990) argue, “Sustainability is basically about good housekeeping. It is essentially about whether, based on the policy currently on the books, a government is headed towards excessive debt accumulation” (p. 8). By contrast, the functional finance view argues that it is involuntary unemployment and excessive unutilized capacity that a government and a nation cannot “afford.” Much as the theoretical foundations for fiscal policies consistent with the philosophy of functional finance have been detailed by other researchers (e.g., Arestis and Sawyer, 2003; Bell, 2000; Forstater and Mosler, 2005; Mosler, 1995, 1997-8; Nell and Forstater, 2003; Wray, 1998, 2003) this paper contributes to the theoretical foundations for a monetary policy complement to these fiscal policies. The corollary here is the importance of recognizing that a nation similarly cannot “afford” high-interest-rate monetary policies if it also wants to pursue true, full employment policy while ensuring that whatever fiscal deficits incurred in the process are not inflationary. The monetary policies implemented by the Fed during 1979:4 – 2000:4 stand out as being remarkably “unsustainable” in this regard. Another necessary—though, admittedly, not sufficient—hurdle to overcome in the progression toward a functional finance-based macroeconomic policy is to abandon analyses based on the flawed IGBC framework currently employed by numerous government offices. In short, if it is true that involuntary unemployment is a frequent—if not persistent—characteristic of a modern capitalist system as Keynes, Minsky, and many others have concluded, then the nation most certainly cannot “afford” to have its policies run according to such a mistaken analytical framework as the one at the heart of the misguided and tragically mislabeled Honest Government Accounting Act.
Abstract: Neoclassical views on fiscal sustainability are based on several assumptions that are inconsistent with accounting and operational realities of the money system, including dangers of “bond vigilantes” in government debt markets and “printing money” is inherently inflationary. Combining these assumptions with the broader world view of monetary policy as the appropriate sole manager of the macroeconomy, neoclassicals essentially define fiscal sustainability as a policy mix in which fiscal policy “gets out of the way” of “monetary dominance”, defined as the central bank's ability to independently pursue an “optimal” monetary policy. This paper presents an alternative view consistent with real-world accounting and monetary operations; a policy mix in which fiscal policy has an active role is shown to be a more sustainable one. Perhaps surprisingly, this turns out to also not be subject to the neoclassical fears or concerns of a policy regime of fiscal dominance.
With the winding down of successive rounds of quantitative easing now concluded, the discussion in monetary policy circles is of a “normalization” back to higher interest rates and an “optimal” strategy based on Taylor-type interest rate policy rules. As St. Louis Fed President James Bullard put it even back in 2015, “[T]he particular [Taylor-type] rule that’s... been around policy circles for the last decade or more... suggests that we should have already lifted off” (Bullard, 2015, p. 19). It is interesting to recall Willem Buiter’s lamentation of the “uselessness of ‘state of the art’ academic monetary economics” that “not only did not allow questions about solvency and illiquidity to be answered. They did not allow such questions to be asked” (Buiter, 2009; emphasis in original). In other words, the models that now say interest rate policy should return to a Taylor-type framework are the same ones that did not incorporate private sector insolvency or illiquidity. But unless there was a “normal,” pre-crisis world where economists and monetary policy makers should have been able to ignore private sector debt and insolvency, then such a “normalization” seems unwarranted. It is reminiscent of Keynes’s famous criticism that “[E]conomists set themselves too easy, too useless a task if in tempestuous seasons they can only tell us is that when the storm is past the ocean is flat again” (Keynes, 1921, p. 80). Returning to the pre-crisis models and policy frameworks is not unlike believing that “the ocean is flat again” now or will be in the very near future. This paper has argued that a sustainable mix of fiscal policy and monetary policies must be understood and designed consistent with the following “principles”: (a) fiscal sustainability is about interest on the national debt more than primary budget balances or the national debt themselves; (b) for currencyissuing governments under flexible exchange rates, interest rates on the national debt are a policy variable, (c) central bank independence can be threatened by the size of a government’s deficit relative to the economy, but not by “being forced into printing money,” (d) government debt has important interactions with private sector debt, (e) the private sector can become dominated by speculative/Ponzi financial positions and this evolution might even be accelerated by tightening monetary policy, and (f) policy rates and interest on the national debt have historically been below GDP growth, and may need to be without large current account surpluses or a fiscal policy approach based on functional finance. These all follow from basic operations and accounting related to government and central bank operations, while at the same time none of them are integrated into the neoclassical approach to modeling monetary economies and designing policy in “normal” times or otherwise.
1⃣Reclaiming the State: A Progressive Vision of Sovereignty for a Post-Neoliberal World (English Edition)https://amzn.to/2Gidk23コ チラはMMTの主張している事が良く分かる 本です。教科書としては中々良いでしょう ね。
2⃣The Rise and Fall of Money Manager Capitalism: Minsky's half century from world war two to the great recessionhttps:// amzn.to/2TFV8lNコチラはミンスキーモーメ ント(金融不安定仮説)で知られるミンス キーの直弟子であるランダルレイが、ミンス キーの主張は「モーメント」ではなく、「半 世紀」と評するべき。という中々面白い本で す。金融危機は一瞬の夢なんてものでは無 く、人為的に起こるように仕組まれていた、 もしくはそうなるように人々は気づかぬうち に向かっていたのであって、「バブルになっ たから」なんていうバカらしい理由は通用し ない。
3⃣Why Minsky Matters: An Introduction to the Work of a Maverick Economisthttps:// amzn.to/2GkPeniコチラは、ミンスキーの直 弟子のランダルレイが師匠の分かりにくくて 複雑で多彩な議論・英語をより分かりやすく しつつミンスキーの重要性を伝えているすご くいい本です。
4⃣The Best Way to Rob a Bank is to Own One: How Corporate Executives and Politicians Looted the S&L Industry (English Edition)https://amzn.to/37ZvCjXコチラは、 銀行業というのが本質的にどのように私たち の世界で動くのか、そしてどのようにして不 安定性を生んでいるのか?という事を解説し た非常に面白い本です。
5⃣Global Imbalances and Financial Capitalism: Stock-Flow-Consistent Modelling (Routledge Frontiers of Political Economy)https:// amzn.to/3jLYezvMMTを理論的に非常に特徴 ある物にしている武器の一つに、「SFCモ デル」があります。こちらはそれの分かりや すい解説+主流派モデルへの代替理論です ね。


 ゆーくん
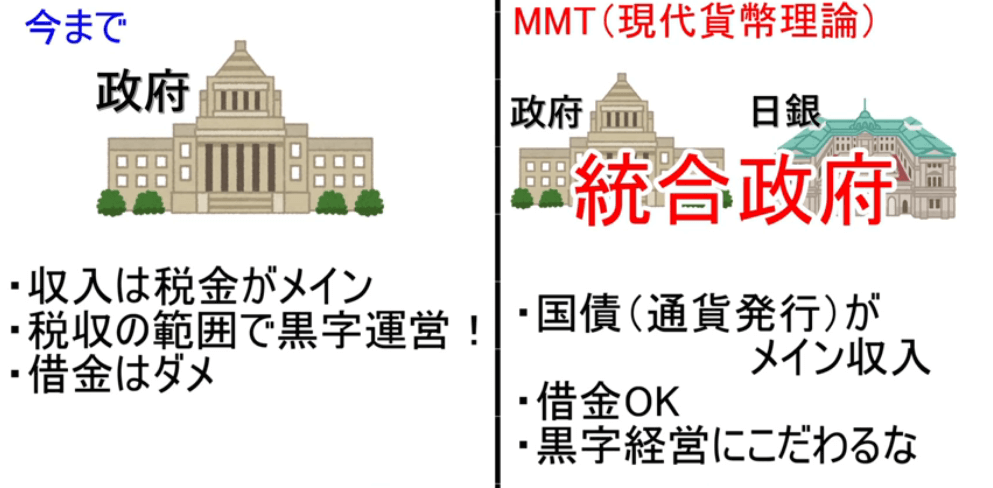


MMTの基礎
返信削除1国定信用貨幣論
(お金で税金払わないと逮捕だから
お金に価値あり)
2機能的財政論 まとめて理論を強化一MMT
(財政の目的は、経済の安定化、
赤字かどうかは大事じゃない)
3内生的貨幣供給論
(中央銀行は世間への
貨幣供給をコントロールできない)
詳細な理論と共にさらに強化したようなもの
返信削除MMTの基礎
1国定信用貨幣論
(お金で税金払わないと逮捕だからお金に価値あり)
2機能的財政論
(財政の目的は、経済の安定化、赤字かどうかは大事じゃない)
3内生的貨幣供給論
(中央銀行は世間への貨幣供給をコントロールできない)
まとめて理論を強化一MMT
(
返信削除MMTの基礎
1国定信用貨幣論
(お金で税金払わないと逮捕だからお金に価値あり)
2機能的財政論
(財政の目的は、経済の安定化、赤字かどうかは大事じゃない)
3内生的貨幣供給論
(中央銀行は世間への貨幣供給をコントロールできない)
まとめて理論を強化
返信削除20分でわかる!経済の仕組み【東大生が教えるMMT(現代貨幣理論)】
https://youtu.be/1lIIoTpxSRY
すごくいい動画なのですが、商品貨幣論と誤解されやすいかも知れません。結縄で検索して下さい。メソポタミアの土器より信用貨幣論が身近になります。
自分は信用貨幣は一対一から成り立つと考えます(計算貨幣は別ですが)。だからコミュニティを前提としません。前作でも採用された国定信用貨幣論という中野剛志氏の造語が一足飛びで二つの概念(イネスの信用貨幣論とクナップの国定貨幣論)を繋げてしまったので初心者が誤解すると危惧しているのです。頭の良い人には伝わると思いますが…中野先生もこの動画(特に前作)も正しいし、有意義であることは間違いなく、応援しております。
【15分で全体がわかる】東大生が教える現代貨幣理論(MMT)入門 後編
返信削除https://youtu.be/Oqnko9Y6Wnw
2020/11/02
MMTの基礎として中野剛志先生の用語「国定信用貨幣論」を採用しています。